university notes that's useful at work as a graduate accountant - P&L

FLIPPING HOUSE
Flipping: a term used primarily in the United States to describe purchasing a revenue-generating asset and quickly reselling it for profit.
Though flipping can apply to any asset, the term is most often applied to real estate and IPO.
RENTAL INCOME
Main residence exemption = exempt from CGT
Check agent statement
Land tax
Land tax online | Revenue NSW - Assessment calculation
Aggregated taxable land value 2,698,333
Less: threshold ( 629,000)
Tax $100 plus balance @ 1.6% 2,069,333 x 1.6% + $100
Total tax payable $ 33,209.33
Discount allowed (90.15) $ 33,119.15

Profit on sale of NCA
Tax reconciliation
NET PROFIT/LOSS PER THE ACCOUNTS
ADD: Taxable profit on sale of NCA
LESS: Accounting profit on sale of NCA
P&L
OTHER INCOME - Profit on Sale of Non-current Assets
BALANCE SHEET
Plant and Equipment
Motor vehicles - at cost 51,448 -> 0
Less: Accumulated depreciation (49,115) -> 0
Profit on sale of NCA 2,333
DR Profit on sale of NCA 2,333
DR Acc depreciation - motor vehicle 49,115
CR Motor vehicles - at cost 51,448
"GST you must pay when you sell property as part of your business."
Pre 01/07/2000: valuation method
Post 01/07/2000: consideration method
Example: Using the consideration method
Bob is a GST registered builder. On 1 December 2002, Bob purchased a block of land for $150,000 from a vendor who was not registered for GST.
Bob paid $550 in conveyancing fees and $7,000 in stamp duty on the purchase of the land.
Bob later constructed a house on the land and sold the house and land for $315,000. Bob chose to use the margin scheme to work out the GST on the sale.
The margin for the sale of the house and land package is $165,000 ($315,000 − $150,000).
The GST Bob must pay on the margin for the sale is $15,000 ($165,000 × 1/11th).
Bob has a tax invoice for the conveyancing fees and can claim a GST credit of $50 ($550 × 1/11th) in the tax period to which the purchase applies.
Bob also holds tax invoices for $110,000 of business purchases he made when building the house. Bob is able to claim $10,000 in GST credits for these purchases.
Bob is not entitled to any GST credits on the stamp duty as GST is not included in the cost.
CAPITAL GAINS
sale of shares - REALISED
Taxable CG Calculation
CG not eligible for discount
Less: Capital loss _
A
Capital Gains eligible for discount
Less: remaining current year capital losses
Less: discount on eligible capital gains
B
Taxable CG (A+B)
Capital losses carried forward
sale of property - UNREALISED
Consideration
Less: agent commission
Less: legals Less:
Purchase price
Stamp duty
Legals
= Capital gains/Loss
Market value movement
Closing balance
Less: Opening balance _
Movement
Add: Proceeds from sales
Add: Disposal of revenue assets
Less: Purchases _
Total market movement
Realised market movement (accg cg)
Profit/loss on disposal of revenue asset
Unrealised market movement


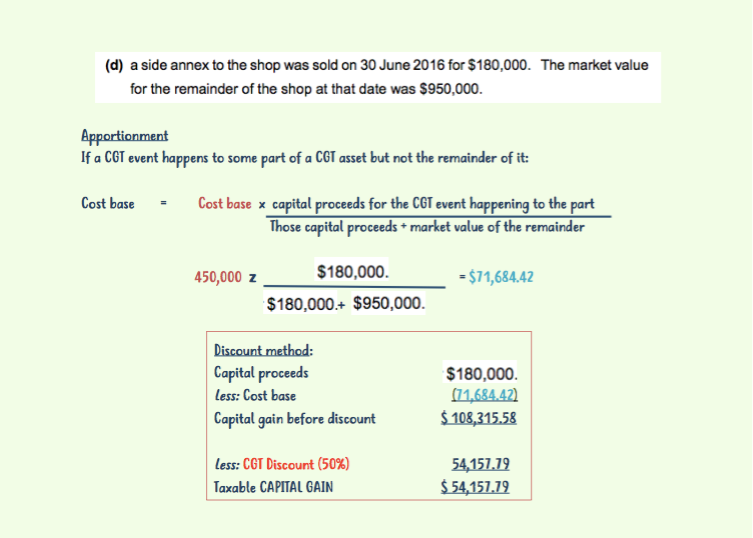
Date: S3 2017
Subject: Revenue Law (BUSL320)
Description: Presentation on CGT
INSURANCE
Non-deductible insurance premiums include:
any insurance premiums paid by a non-complying SMSF
payments for insurance that covers events other than death, the existence of a terminal medical condition, or temporary or permanent disability (for example, funeral insurance).
Trauma insurance is non-deductible


Comments